November 16, 2026
Buying Before You Sell in the GTA? How Bridge Financing Actually Works
Share this article:


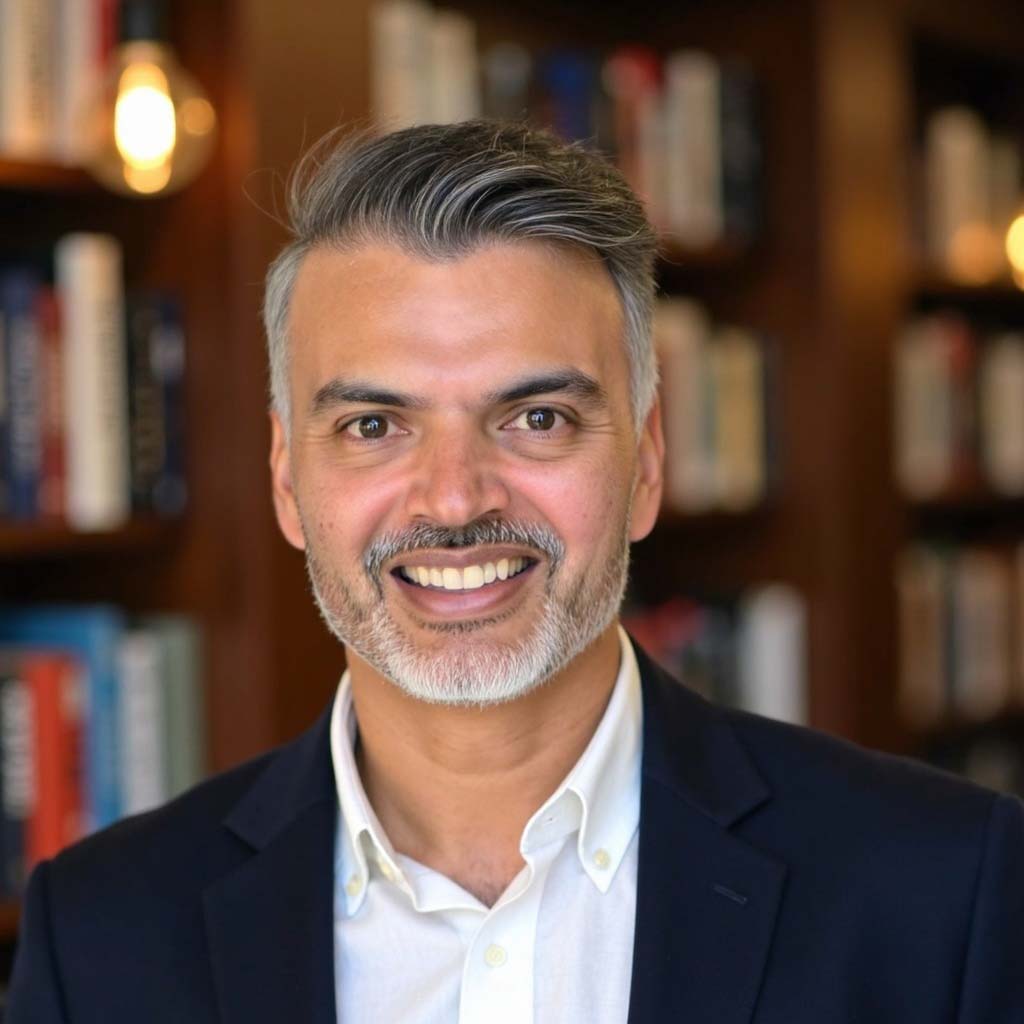
Manzeel is an award-winning Mortgage Broker and the Owner of the Toronto-based mortgage, Everything Mortgages.
With 16 years of experience in the Canadian mortgage industry and a formal background in mortgage underwriting, Manzeel’s lending expertise gives him unique insight into whether a deal is feasible which empowers his clients to make more informed lending decisions faster.
He has been recognized as one of Canada’s Top 10 Mortgage Brokers by the national Canadian Mortgage Professionals (CMP) Association. Him and his team of 18 mortgage agents are proud to offer a mortgage experience that's built on honesty, trust, and integrity. He prides himself on the brokerage’s dedication to deliver an excellent client experience throughout the entire home loan process from pre-approval to post-funding.
Since moving to Toronto in 1998, Manzeel has successfully launched and scaled several businesses from the ground up, ranging from a mortgage brokerage and a vast real estate investment portfolio to a private financing eCommerce platform. He continues to be a leader in the real estate industry as he uses his analytical expertise to seek new real estate investment opportunities.
As a tech junkie and avid sports enthusiast, when Manzeel’s not working with clients, you can find him reading technology blogs, playing squash or watching tennis with his two boys.
Every fall I get the same call. “Manzeel, we found the house. Our place is sold, but our closing is 5 weeks after the new one. What do we do?”
Most of the time the answer is a bridge loan. It’s one of the most routine things we set up, but a lot of people don’t hear about it until the last minute, which is exactly when it gets stressful. So here’s how it works, plain and simple.
What bridge financing is
A bridge loan is a short-term loan against the equity in the home you’re selling. It covers the gap between your purchase closing and your sale closing.
Basically your down payment is sitting inside your current house. The bridge lender advances that money early so you can close on the new place on time. When your sale closes, the proceeds pay off the bridge. Done.
You only pay interest for the days you actually use it.
What lenders need to approve it
This is where files go sideways, so pls read this part.
- A firm sale on your current home. Not an accepted offer with conditions still open. Financing and inspection conditions have to be waived and the deposit paid. This is the #1 reason bridge requests get declined.
- A firm purchase agreement on the new home, also with conditions removed.
- An approved mortgage on the new home. With most banks and lenders the bridge comes with the new mortgage. It’s not a standalone product, so it’s set up with the same lender.
- Enough equity. The lender works off your firm sale price, minus your current mortgage payout, realtor commission, legal and other closing costs. Whatever’s left is roughly what they’ll bridge.
- Both closing dates confirmed in the agreements.
How long and how much
Most banks and A lenders cap bridge financing at around 90 days. Some will go to 120. If your gap is longer than that, you’re usually looking at private financing instead (more on that below).
Cost wise, bank bridge loans are typically priced at prime plus a few points (commonly quoted in the prime + 2% to prime + 5% range), plus a setup or admin fee, usually a few hundred dollars. Your lawyer may charge a bit extra too, since they’re handling an extra loan on closing.
The rate looks high next to a regular mortgage rate. But the number that matters is total dollars, and that depends on how few days you’re in it.
Quick example (numbers are for illustration only): say you need $150,000 bridged for 30 days at an expected rate around 8%. That’s roughly $990 in interest, plus the admin fee. Compare that to rushing your sale, taking a lower offer, or moving twice and paying for storage and a short-term rental. For most of my clients the bridge is the cheaper option by a lot.
What if your house isn’t sold yet?
This is the tougher one. If you bought first and your current home isn’t sold (or the sale is still conditional), a regular bank won’t do a bridge loan. The firm sale is their security.
Your options at that point:
- HELOC on your current home. If you already have one with room on it, this is often the cheapest way to free up the down payment. If you don’t have one, it’s worth setting up before you start house hunting. Much harder to get once you’ve bought.
- Short-term private mortgage. A private lender can lend against your current home’s equity for a few months until it sells. It works, but it costs a lot more than a bank bridge: higher rate plus a lender fee and broker fee. I only recommend it when the math makes sense and there’s a clear exit (the sale).
- Push the closing date. If you’re still negotiating the purchase, ask for a longer close. A 90 or 120-day closing gives you room to sell first. Talk to your realtor before you write the offer, not after.
- Carry both mortgages. Some clients qualify to carry both homes for a bit. You need the income to support both payments on paper, so this one depends a lot on your file.
Mistakes I see a lot
- Calling about the bridge the week before closing. Set it up when you arrange the new mortgage. One lender, one set of instructions to your lawyer.
- Thinking a conditional sale counts. It doesn’t. Until conditions are waived, there’s nothing to bridge against.
- Overestimating equity. Don’t forget commission, legal fees, and any mortgage penalty on your current home. Those all come off the top.
- Not checking your current mortgage terms. If you’re breaking a fixed rate early, the penalty can be big. Sometimes porting your mortgage to the new home makes more sense, and it can be combined with a bridge. Worth a look before you decide.
My advice
If you’re even thinking about moving up (or down) in the next few months, talk to me before you write an offer. We’ll look at your equity, your current mortgage, and what the timing could look like. That way if the dates don’t line up, you already know your plan B and what it costs.
Bridge financing isn’t complicated. It just needs to be set up early.
Questions about buying before you sell? Reach out anytime.
Call 416-840-6368
Email: info@everythingmortgages.ca
Web: everythingmortgages.ca
Manzeel Patel, Mortgage Broker
Everything Mortgages | Brokerage Lic# 12755
This article is general education, not financial advice. Bridge loan availability, pricing and terms vary by lender. All financing is subject to lender approval, and costs depend on your file and how many days you use the bridge.