September 29, 2026
Fixed or Variable? How I Help Toronto & GTA Clients Decide Right Now
Share this article:


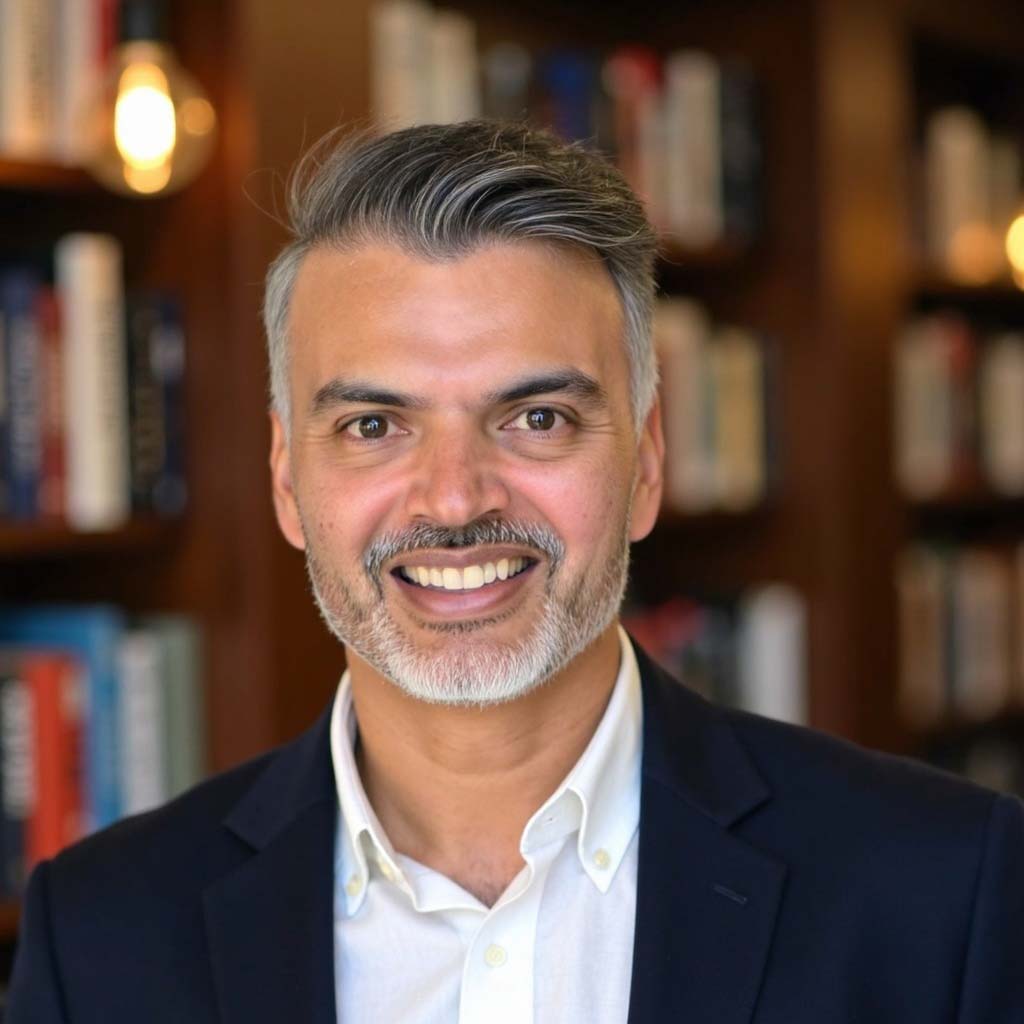
Manzeel is an award-winning Mortgage Broker and the Owner of the Toronto-based mortgage, Everything Mortgages.
With 16 years of experience in the Canadian mortgage industry and a formal background in mortgage underwriting, Manzeel’s lending expertise gives him unique insight into whether a deal is feasible which empowers his clients to make more informed lending decisions faster.
He has been recognized as one of Canada’s Top 10 Mortgage Brokers by the national Canadian Mortgage Professionals (CMP) Association. Him and his team of 18 mortgage agents are proud to offer a mortgage experience that's built on honesty, trust, and integrity. He prides himself on the brokerage’s dedication to deliver an excellent client experience throughout the entire home loan process from pre-approval to post-funding.
Since moving to Toronto in 1998, Manzeel has successfully launched and scaled several businesses from the ground up, ranging from a mortgage brokerage and a vast real estate investment portfolio to a private financing eCommerce platform. He continues to be a leader in the real estate industry as he uses his analytical expertise to seek new real estate investment opportunities.
As a tech junkie and avid sports enthusiast, when Manzeel’s not working with clients, you can find him reading technology blogs, playing squash or watching tennis with his two boys.
Bank of Canada held the overnight rate at 2.25% on Sept 2, 2026. Next announcement is Oct 28.
That doesn’t automatically tell you whether to take a fixed or a variable mortgage. Your lender’s quote, your budget, and what you plan to do with the house in the next few years still decide that.
Here’s how I walk Toronto and GTA clients through it.
What each product actually is
Fixed
Your rate is locked for the term (often 3 or 5 years). Payment stays the same. Easier to budget. Break cost if you exit early is usually the Interest Rate Differential (IRD) or 3 months’ interest — whichever the contract says. IRD can get expensive if rates have dropped a lot since you locked.
Variable
Your rate moves with the lender’s prime, which generally tracks the Bank of Canada overnight rate. Payment either floats with the rate, or stays fixed while more/less goes to principal (depends on the product). Break cost is often 3 months’ interest — usually simpler than IRD, but still not free.
Neither one is “always better.” It’s a tradeoff.
What the BoC hold means (and what it doesn’t)
A hold at 2.25% means variable products aren’t getting an automatic cut from that announcement. It also doesn’t freeze fixed rates — those move more with the bond market.
BoC also flagged higher upside risks to inflation (energy, trade/tariffs). So I’m not telling clients to bet the farm on a big cut before Oct 28. I’m also not telling them rates can only go one way.
If you’re closing or renewing in the next 60–90 days, decide based on your payment comfort, not a guess on the next press conference.
When fixed usually makes sense
I lean fixed when:
- The payment has to be predictable (one income, new purchase, thin buffer).
- You’re fine paying a bit more for sleep-at-night certainty.
- You’re unlikely to sell, refinance, or break the mtg early in the term.
- The fixed quote is close enough to variable that the “savings” on variable don’t pay you for the risk.
If a $150–200 swing in the monthly payment would hurt, stop overthinking the forecast. Take the payment you can carry.
When variable is worth a real look
Variable can make sense when:
- You have room in the budget if prime moves up.
- You might sell, refinance, or restructure inside the term (break cost is often cleaner).
- You’re okay watching the rate and adjusting if needed.
- The gap vs fixed is wide enough that you’re being paid for the risk.
A cheap variable that blows up your cash flow isn’t a win. Run the payment at a higher rate before you sign — not after.
Don’t pick on rate alone
When I compare options for a client, I put these side by side:
- Contract rate and payment (today)
- Stress payment — what if variable jumps 1–2%?
- Term length — 3 yr vs 5 yr changes how long you’re locked
- Prepayment room — lump sum / payment increase privileges
- Break rules — IRD vs 3 months’ interest
- Fees — legal, appraisal, discharge, any cash-back clawback
- Your plans — buy, sell, reno, HELOC, debt consolidation in the next 2–3 years?
A “great” rate with terrible break terms is a problem if life changes.
Purchase vs refinance vs switch (quick note)
- Purchase / new mtg: You’re picking the product fresh. Pre-approval still matters so you know the payment before you offer.
- Refinance: You’re rewriting the deal — product choice + equity/debt goals both matter.
- Switch at maturity: Often no IRD because the term is ending. Still compare fixed vs variable on the new term, and watch legal/admin costs.
If you’re mid-term and thinking of breaking to “catch a better rate,” run the penalty first. Sometimes waiting for maturity or using a HELOC/second is cleaner. I wrote a separate renewal checklist for fall renewals if that’s your situation.
First-time buyers: one extra lever
If you’re a first-time buyer (or buying a new build) on an insured mtg, you may have access to a 30-year amortization. That lowers the monthly payment vs 25 years, but you pay more interest over the life of the loan.
Longer amort can help you qualify and keep cash flow sane. It doesn’t replace the fixed vs variable decision — it just changes the payment math. We can model both.
What I need from you to give a straight answer
Send me:
- Purchase price / remaining balance (and approx closing or maturity date)
- Down payment or equity
- Income type (T4, self-employed, etc.)
- Other debts (car, cards, HELOC)
- How long you expect to keep the property / this mtg
- How much payment swing you can handle monthly
I’ll map fixed vs variable (and sometimes a shorter fixed term) against your numbers — not a blog generic.
Bottom line
BoC at 2.25% with Oct 28 coming up is useful context. It’s not the decision.
Pick the product where the payment works, the break rules fit your plans, and you’re not gambling money you need for groceries and property tax.
If you want me to run fixed vs variable against your numbers, send the basics and I’ll map the options.
Call 416-840-6368
Email: info@everythingmortgages.ca
Web: everythingmortgages.ca
Manzeel Patel
Mortgage Broker, Everything Mortgages, Lic# 12755